
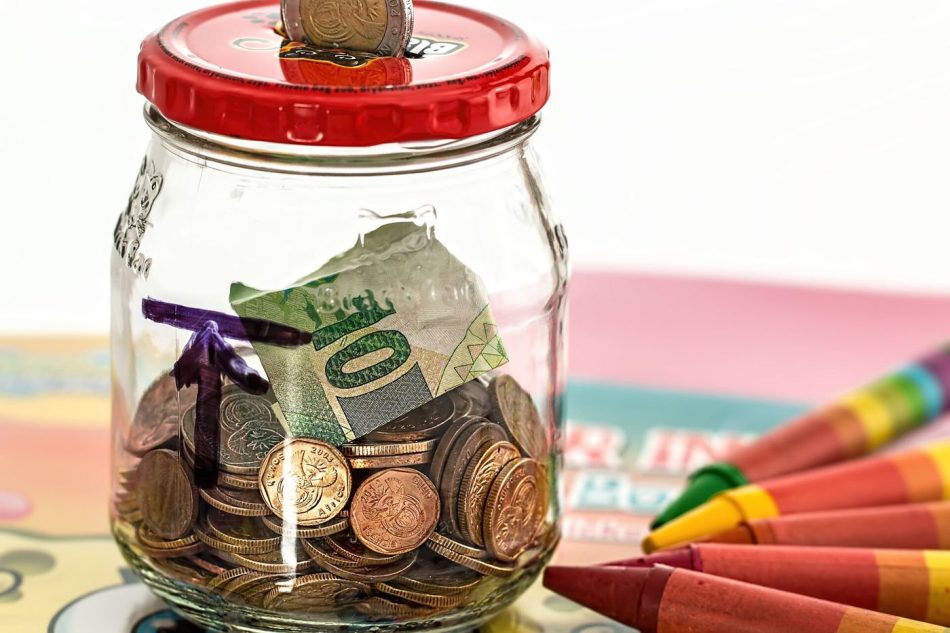
Households are building emergency funds through small, regular contributions, turning a daunting savings goal into a manageable habit.
Households are building emergency funds through small, regular contributions, turning a daunting savings goal into a manageable habit. Financial advisers recommend keeping three to six months of essential spending in an easily accessible account, enough to cover a broken boiler, a car repair or a sudden loss of income without resorting to expensive borrowing. For many families, that target once seemed out of reach, but a growing number are reaching it by automating a modest transfer on payday, starting with as little as a few pounds or dollars a week. The approach works because it removes the decision: the money leaves the account before it can be spent, and the balance grows quietly in the background. Surveys suggest that households with even a small emergency cushion report less stress and are far less likely to fall behind on bills when something goes wrong. The habit matters more than the amount, and advisers say starting small beats waiting for the perfect moment.
What the Evidence Shows
Building the fund is only the first step, and advisers say the rules for using it matter just as much. The money should be kept separate from everyday spending, ideally in a different account, so it is not dipped into for holidays or treats. When an emergency does arrive, the fund should be used without guilt, since that is exactly what it is for, and then rebuilt gradually once the crisis has passed. Others split it between an instant-access account for urgent needs and a slightly higher-paying account for larger reserves. Employers and banks are also helping, with some workplaces offering payroll savings schemes that divert a small sum automatically. Consumer groups note that low-income households face the hardest challenge, since finding any spare money is difficult. For most families, the emergency fund is the foundation of financial security, and the peace of mind it brings is worth more than the interest it earns. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following emergency fund savings say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by emergency fund savings are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with emergency fund savings will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.